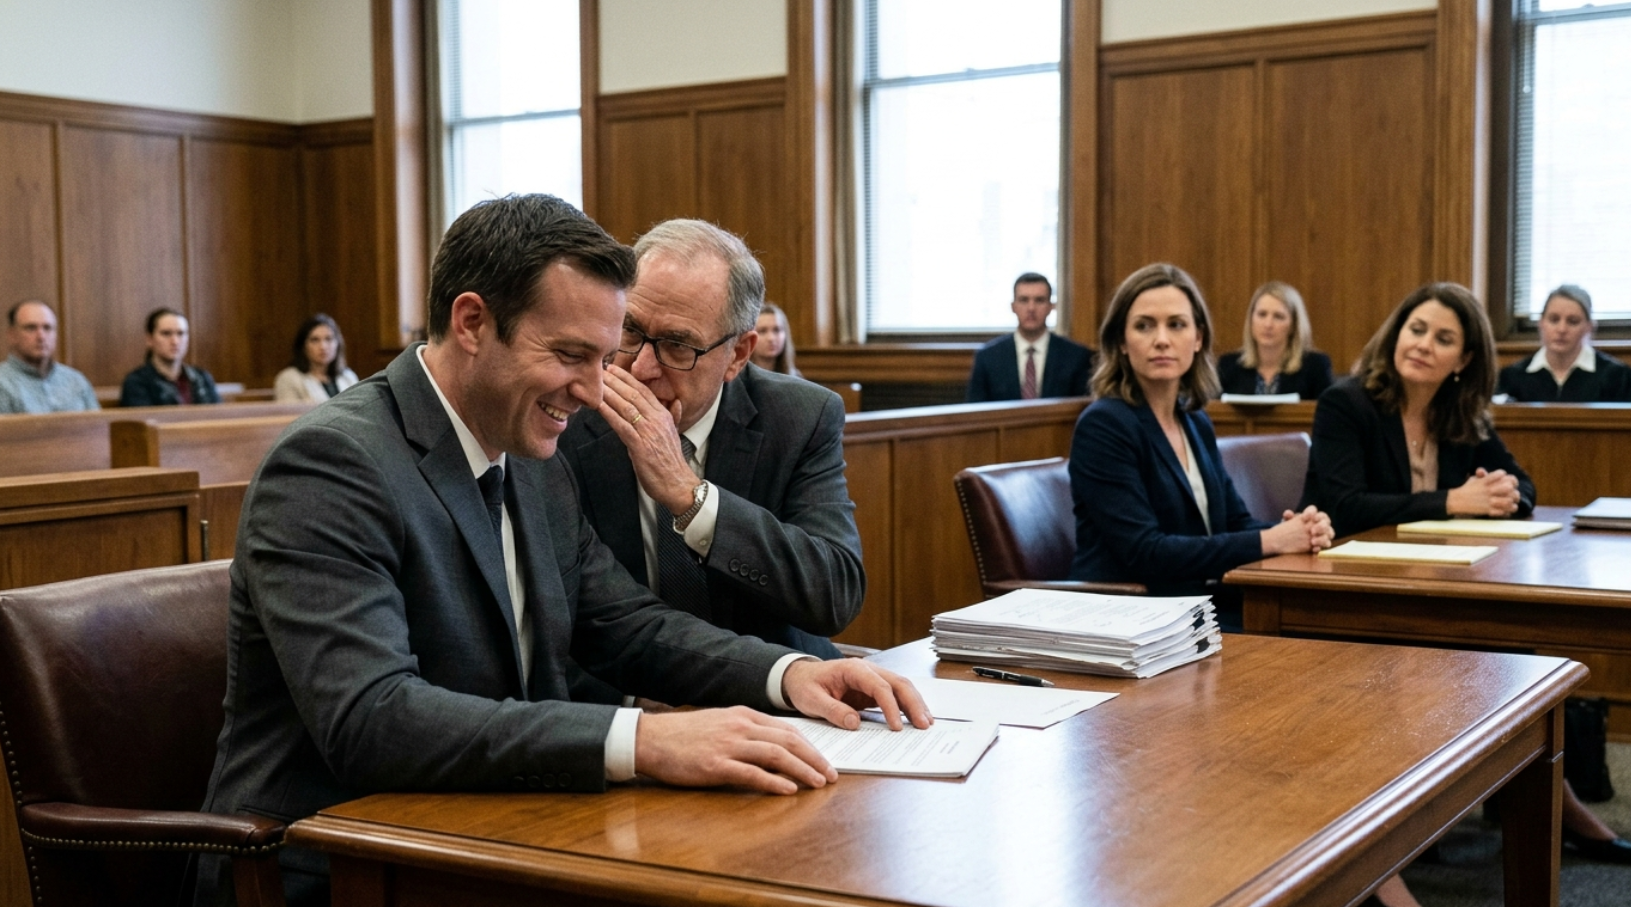
His smug demeanor shattered the instant he read the attached addendum.
David’s smile disappeared so quickly it was almost startling.
One second, he was leaning back in his chair like a man posing for a photograph after a championship game.
The next, his shoulders went rigid.
His attorney, Richard Fallon, whispered something else.
David grabbed the agreement.
Not the decree itself.
The attachment.
Four pages.
Single-spaced.
He flipped to the second page.
Then the third.
His eyes moved faster.
“What is this?”
His voice carried farther than he intended.
The judge looked up.
“Mr. Vance?”
Richard put one hand lightly on David’s arm.
“Not here.”
David jerked away from him.
“No. What is this?”
Jessica, sitting beside me, did not move.
Neither did I.
The judge’s expression hardened.
“Mr. Vance, you are in my courtroom. If you have a question for your attorney, you may confer quietly.”
David lowered his voice, but not enough.
“I thought I was getting the house free and clear.”
Richard whispered something.
David’s face changed again.
Not anger yet.
Fear.
That was when Jessica finally looked at me.
Only for a second.
Her eyes said the same thing mine probably did.
He really didn’t know.
I had wondered until that moment whether David’s arrogance had been an act.
Whether he understood what he was taking and simply believed he could absorb it.
Apparently not.
He had seen the assets.
He had not bothered to understand the obligations attached to them.
Which was ironic.
Because that was exactly how he had treated our marriage.
He wanted ownership.
He never paid attention to what ownership required.
The judge cleared his throat.
“Mr. Fallon, does your client need additional time to review the agreement?”
Richard looked like a man trying to stop a boat from sinking with a napkin.
“Your Honor, my client has reviewed and signed the settlement.”
David turned toward him.
“You told me—”
Richard’s jaw tightened.
“I told you repeatedly to review the schedules.”
“I did.”
“No, David,” Richard hissed. “You reviewed the asset page.”
I looked down so no one would see the involuntary smile trying to form.
Jessica pressed her lips together.
The judge spoke again.
“Mr. Vance, I asked you earlier whether you understood the settlement.”
David stared at him.
“I—”
Richard leaned close.
“Careful.”
That one word seemed to restore something.
David sat straighter.
“Yes, Your Honor.”
“You were represented by counsel throughout negotiation?”
“Yes.”
“You entered this settlement voluntarily?”
His eyes slid toward me.
I held his gaze.
“Yes.”
“And no one forced you to accept the allocation of property and liabilities?”
David’s nostrils flared.
“No.”
“Then unless counsel is telling me there is a legal defect in the agreement, we are going to finish.”
Richard said, “There is no defect, Your Honor.”
David looked at him as though he had been stabbed.
The judge signed.
Just like that.
Twelve years of marriage ended with a pen stroke.
But the thing David had not understood was that the divorce had never really been about who got the house.
Or the cars.
Or the money he could see.
It was about what those things were attached to.
And six months earlier, David had made the mistake of believing I knew as little about our finances as he wanted me to.
I didn’t.
Not anymore.
David had always considered himself the financial brain of our marriage.
He worked in commercial development.
Not glamorous skyscrapers or luxury resorts.
Mostly regional retail centers, medical offices, and suburban mixed-use projects.
He knew bankers.
He knew contractors.
He knew how to say “capital stack” in a way that made normal people feel they should nod.
I worked too.
For the first seven years of our marriage, I was an interior architect.
Then Sam was diagnosed with a language-processing disorder and severe dyslexia when he was five.
His school could help, but not enough.
There were evaluations.
Specialists.
Occupational therapy.
Tutors.
Meetings.
So I reduced my hours.
Not because David ordered me to.
At least not directly.
We made the decision together.
Or I thought we did.
“You can always go back full-time later,” he had said.
Sam needed stability.
Someone needed to coordinate everything.
David’s work had him traveling constantly.
My firm offered part-time consulting.
It made sense.
For a while.
Eventually “Claire is reducing hours temporarily” became “David is the real earner.”
Then it became “Claire doesn’t understand the pressure I’m under.”
Then “I handle the money because I deal with this stuff professionally.”
And eventually:
“You don’t need to worry about that.”
That sentence can sound reassuring when you trust someone.
It can also become a curtain.
By the time David asked for the divorce, he controlled almost all the information.
I knew roughly what we owned.
The Scottsdale house.
Two vehicles.
His Porsche 911.
My Lexus SUV.
Investment accounts.
Savings.
Retirement.
An interest in two development partnerships.
At least that was what I thought existed.
David made it sound simple.
“I want the house, the cars, and the savings accounts. Everything.”
Then the pause.
“You can keep the boy.”
The boy.
I will never forget that phrase.
People later assumed that was the moment I began planning revenge.
It wasn’t.
It was the moment I stopped caring about winning the way David defined winning.
That distinction mattered.
Because before that sentence, some part of me still imagined a normal divorce.
Sad.
Hostile maybe.
But civilized.
We would divide things.
Co-parent.
Attend Sam’s school events from different sides of the room.
Eventually learn how to speak without hurting each other.
Then David reduced our son to the item he didn’t want in the division.
The cars mattered.
The house mattered.
The accounts mattered.
Sam was disposable.
Something inside me settled.
Not broke.
Settled.
The next morning, after David left for work, Sam came downstairs carrying the solar-system model he had been making the night before.
Saturn’s ring was crooked.
He was furious about it.
“It looks stupid.”
“It looks like Saturn after a traffic accident.”
He stared at me.
Then laughed.
I helped him reglue the ring.
He had no idea his father had announced twelve hours earlier that he did not want him.
I intended to keep it that way as long as possible.
Jessica had been my first call.
She was a friend of a former colleague and had practiced family law for nineteen years.
When I told her David wanted all major assets and no meaningful custody, she immediately started listing options.
Temporary orders.
Financial disclosures.
Custody evaluation.
Asset restraint.
Forensic accounting.
I barely heard her.
“I want him to have it.”
She stopped.
“What?”
“The things.”
“The house?”
“Yes.”
“The vehicles?”
“Yes.”
“The liquid accounts?”
“If that’s what he wants.”
“Claire, absolutely not.”
“I want Sam.”
“Custody and property are separate issues.”
“I know.”
“You contributed to that estate.”
“I know.”
“You put almost eighty thousand dollars of your premarital savings into the Scottsdale remodel.”
“I know.”
“You are entitled to have that analyzed.”
“I know.”
She slammed her pen down.
“Then why are you talking like someone who plans to walk away barefoot?”
Because I knew one thing David did not.
Three weeks before he asked for the divorce, I had opened the wrong envelope.
It came from Desert National Bank.
David received dozens of business letters.
Most went to his office.
This one came home.
The envelope was addressed to David Vance.
Underneath, in smaller letters:
Vance Development Group, Guarantor.
I was about to put it on his desk when I noticed our home address in the loan reference line.
Not mailing address.
Collateral address.
I opened it.
Yes, technically it was addressed to my husband.
No, I do not regret opening it.
Inside was a notice that a commercial loan was approaching a covenant review date.
The outstanding balance was $2.84 million.
At the bottom:
Additional collateral includes residential real property located at—
Our address.
I read it three times.
Then a fourth.
The house David loved showing off was listed as collateral for a business obligation I had never heard of.
I waited until he came home.
He was irritated before I even finished asking.
“It’s complicated.”
“Why is our house securing a commercial loan?”
“It isn’t.”
I handed him the letter.
His expression changed.
Only for a second.
Then came the annoyance.
“That’s just boilerplate.”
“Is the house collateral or not?”
“Claire, you don’t understand how these facilities are structured.”
“Then explain it.”
“I’m tired.”
“David.”
“Jesus.”
He threw his keys onto the counter.
“It’s cross-collateralization. It doesn’t mean anything unless there’s a default.”
“Can the business default?”
“Any business can technically default.”
“That isn’t an answer.”
“Because it’s a stupid question.”
I remember how calmly he said it.
Not shouted.
Dismissed.
A stupid question.
I had spent years making design presentations to developers who did not know the difference between veneer and solid wood, and I had never called their questions stupid.
But David did it whenever information threatened his advantage.
I did not argue.
That surprised him.
I simply said:
“Okay.”
He relaxed.
That was his mistake.
The next morning, I photographed the letter.
Then I started looking.
I did not hack anything.
I did not steal passwords.
I went through documents I legally had access to.
Tax returns.
Joint account statements.
Our closing file.
Property records.
Insurance correspondence.
Arizona Corporation Commission filings.
County recorder documents.
David was right about one thing.
It was complicated.
But complicated is not the same as unknowable.
And once I realized I needed help, I stopped trying to understand it alone.
My first call had been to our CPA.
He became extremely cautious the moment I asked whether the house secured business debt.
“I think you should discuss this with David.”
“That isn’t what I asked.”
“I prepare the joint return, Claire. I don’t advise on David’s development entities.”
“Do I have ownership in those entities?”
Another pause.
“That’s something you should discuss with counsel.”
Counsel.
Not husband.
Counsel.
That word told me enough.
I hired Jessica before David ever asked for a divorce.
Not to file.
To understand.
Jessica brought in a forensic accountant named Martin Alvarez.
Martin was sixty-three, wore cheap reading glasses, and had the patience of a person who had spent forty years catching expensive liars through boring spreadsheets.
The first time we met, I brought two banker boxes.
He asked me one question.
“What are you afraid is true?”
I answered:
“That my husband has risked our house.”
Martin nodded.
“And what are you hoping is true?”
“That I misunderstood the letter.”
He looked at me for a long moment.
“Good. That means you are still capable of following facts instead of hunting for confirmation.”
I liked him immediately.
Two weeks later, he called.
“You did not misunderstand.”
The house had been used as additional collateral.
So had one of our investment accounts.
And, potentially, a reserve account I had always thought was simply savings.
The structure involved three related development entities.
Vance Development Group.
Copper Ridge Retail Partners.
And a company called DV Opportunity Fund II.
“DV?” I asked.
Martin looked at me over his glasses.
“David Vance.”
Of course.
The largest loan financed a retail redevelopment outside Mesa.
The project had been struggling.
Two tenants went bankrupt.
Construction costs exceeded projections.
Interest rates rose.
A refinancing failed.
David responded the way highly leveraged people sometimes do when the numbers stop cooperating.
He borrowed elsewhere.
Then borrowed again.
Then moved money.
Not necessarily illegal.
Not necessarily fraud.
But aggressive.
He personally guaranteed portions of the debt.
Then he pledged marital assets to support those guarantees.
“How much exposure?” I asked.
Martin did not answer immediately.
“That depends on what fails.”
“Worst case.”
“Several million.”
I actually laughed.
He waited.
“Sorry.”
“You don’t have to apologize.”
“We don’t have several million dollars.”
“No.”
“So what happens?”
“Creditors pursue collateral and guarantors according to the loan documents.”
“Our house?”
“Potentially.”
“The savings?”
“Potentially.”
“The cars?”
“Less direct, but in a collection scenario personal assets become part of the discussion depending on ownership and exemptions.”
I felt sick.
“Does David know?”
Martin removed his glasses.
“Claire.”
“Yes?”
“He signed the guarantees.”
Right.
Of course he knew.
That was the moment betrayal changed shape.
The divorce was not the first attack.
The secrecy was.
I went home that evening and made spaghetti.
Sam complained about the sauce having visible onion pieces.
David came home at seven forty.
He kissed my cheek.
He poured wine.
He talked about a contractor dispute.
I watched him move around the kitchen and wondered how someone could know that our home secured millions in business obligations and still complain because I bought the wrong sparkling water.
At one point, he looked at me.
“What?”
“Nothing.”
“You’re staring.”
“I’m tired.”
“Go to bed early.”
Like that.
So ordinary.
Three weeks later, he asked for the divorce.
At first, Jessica assumed the timing was related.
Maybe David wanted to reposition assets before a business collapse.
Maybe he believed divorce could insulate some property.
Maybe he planned to take the assets and later negotiate with creditors.
We did not know.
So we documented.
That was when Martin found something more important.
The Scottsdale house was beautiful.
Six bedrooms.
Five and a half baths.
Pool.
Wine cellar.
Outdoor kitchen.
Guest casita.
David told people it was worth $2.7 million.
He was close.
The problem was debt.
First mortgage:
$1.21 million.
Home-equity line:
$410,000 outstanding.
Business collateral exposure:
not technically another mortgage balance, but enforceable under specified default conditions.
There was also a pending property-tax correction because David had claimed an exemption structure our accountant was already questioning.
Then there were the cars.
My Lexus had equity.
Approximately $21,000.
The Porsche did not.
David had rolled an older auto loan into it.
He owed almost exactly what the car was worth.
The savings accounts?
That was the clever part.
On paper, they contained nearly $460,000.
When David said he wanted the savings, Jessica looked at me as if I were insane for agreeing.
Then Martin traced their purpose.
A substantial portion was not ordinary savings.
It was required liquidity.
Reserve funds connected to development guarantees.
One account had a sweep agreement.
Another had been pledged under a control agreement to Desert National.
David could see the balance.
He could even brag about the balance.
But he did not have the freedom he implied.
The money was standing behind risk.
“What happens if he takes the accounts in divorce?” I asked.
Martin smiled for the first time.
“That depends on how the settlement is written.”
That was when my strategy formed.
Not revenge.
Separation.
Real separation.
David wanted the house.
Fine.
But if he wanted the house, he would take the encumbrances, known liens, contractual obligations, and responsibility for debts allocated to it.
He wanted the investment and reserve accounts.
Fine.
But he would take them subject to any pledges, control agreements, and business claims.
He wanted the Porsche.
Fine.
He would take the loan.
He wanted “everything.”
Fine.
Everything included burdens.
Jessica hated it.
Not legally.
Emotionally.
“You’re leaving value on the table.”
“Maybe.”
“Not maybe.”
We were in her office late one afternoon.
She had three yellow pads covered with numbers.
“If the Mesa project recovers, David could end up with substantial equity.”
“I know.”
“If property values rise, the house could be worth significantly more.”
“I know.”
“If the creditor release goes favorably, some of the reserve funds could become available.”
“I know.”
She leaned forward.
“Then explain this to me.”
I looked at the custody proposal.
David had asked for alternate holiday visitation “as mutually agreed.”
No regular overnights.
No school-week custody.
No decision-making authority except access to records.
He was effectively asking to be Sam’s father when convenient.
He did not even fight when Jessica proposed that I receive final authority for educational and medical decisions.
Sam’s two most important areas.
“He doesn’t want him.”
Jessica softened.
“I know.”
“I don’t want to spend three years fighting over money with someone who is willing to walk away from his child.”
“That doesn’t mean you give up financial security.”
“I’m not.”
“Claire, you are giving him assets worth millions gross.”
“Gross.”
She hated when I said that.
“Do not get cute.”
“I’m not.”
I opened the other folder.
Inside were documents Martin had helped me understand.
My separate retirement account from before the marriage.
A small inheritance from my grandmother held separately.
My current consulting income.
And one asset David had never valued because it had never impressed him.
My twenty percent ownership interest in Harlow Studio.
The architecture firm where I worked before reducing hours.
When I stepped back, the founding partners offered me a small equity stake instead of a larger salary.
David called it “paper ownership in a tiny design shop.”
He once asked why I didn’t sell it and put the money into “something real.”
The firm grew.
Quietly.
Healthcare design.
Hospitality.
Senior living.
Then municipal projects.
Three months before David demanded divorce, Harlow began confidential acquisition discussions with a national engineering company.
I had signed a nondisclosure agreement.
David knew none of it.
At the time of our marriage, my initial stake had been documented as separate property.
Additional portions acquired during marriage complicated things, but the prenup-like ownership agreement among partners and our marital records helped trace the interest.
Jessica and Martin were conservative about its classification.
Some value could be marital.
Some separate.
But the likely acquisition value of my interest, after taxes and adjustments, could exceed what I was walking away from in net marital equity.
Especially once David’s liabilities were included.
Jessica stared at me.
“You’re counting on a deal that hasn’t closed.”
“No.”
“Then what are you doing?”
“I’m deciding that Sam and peace are worth more than extracting the last dollar from David.”
That was true.
The Harlow deal was not the strategy.
It was insulation.
There is a difference.
If the acquisition died tomorrow, I could still work.
I could rent.
I could buy something smaller later.
I could rebuild.
What I did not want was David using every chandelier, bank account, and appraisal as a reason to remain entangled with me for years.
“But why not insist on cash?” Jessica asked.
“Because he’ll fight.”
“He’s already fighting.”
“No. Right now he thinks he’s winning.”
She stared at me.
I continued.
“The more he believes he’s winning, the more likely he is to sign clean responsibility for the debts.”
Jessica’s expression changed.
“You want indemnification.”
“I want release.”
That was the real prize.
I wanted my name off every possible business obligation.
I wanted David responsible for the liabilities attached to the assets he demanded.
I wanted formal indemnification.
I wanted cooperation with lenders to secure releases where possible.
I wanted no claim on his development companies.
No share of future upside.
No responsibility for future collapse.
Clean lines.
Martin called it de-risking.
Jessica called it leaving money behind.
I called it getting out.
Mediation began six weeks later.
David arrived wearing a navy suit and confidence.
He had a new haircut.
No wedding ring.
He had also started seeing someone.
I knew because Sam accidentally mentioned “Dad’s friend Madison.”
Sam had met her once at lunch.
I almost objected.
Then I asked myself whether I cared because it affected Sam or because it hurt me.
Mostly the second.
So I said nothing.
David’s opening demand was absurd.
House.
Both cars.
Investment accounts.
Most savings.
His development interests.
His retirement.
His personal property.
He was willing to let me keep:
my checking account,
personal belongings,
Harlow interest,
and primary custody of Sam.
He proposed child support based on a number so low Jessica nearly laughed.
She countered.
David refused.
Then something fascinating happened.
He became more generous about child support when we stopped pushing hard on property.
That told me exactly where his priorities were.
We increased support.
Secured health insurance.
Agreed on private educational therapy expenses.
Allocated uncovered medical costs.
Established a life-insurance requirement with Sam as protected beneficiary through a trust arrangement.
Then custody.
David barely argued.
No Wednesday dinners.
No alternating weeks.
No demand for fifty-fifty.
He wanted one weekend per month “when work permitted,” certain holidays, and two weeks in summer.
Jessica asked me privately if I wanted to push him toward more parenting time.
“No.”
“Sam may want his father.”
“If David wants Sam, he knows where the door is.”
“That is not how parenting plans work.”
“I know.”
I took a breath.
“I’m not going to force an eight-year-old to spend half his life with a parent who calls him ‘the boy’ when he talks about divorce.”
Jessica nodded.
We kept the schedule limited but allowed expansion by mutual agreement and Sam’s best interests.
Then property.
This was where David became animated.
The house mattered enormously to him.
I understood why.
He had built an identity around it.
Business dinners by the pool.
Wine tastings in the cellar.
Sunday football in the media room.
His friends called the place Vance Manor as a joke.
David pretended to hate it.
He loved it.
At mediation, his attorney asked:
“Claire is prepared to waive her claim?”
Jessica answered carefully.
“Subject to debt allocation and releases.”
David barely listened.
“What about the furniture?”
I looked at him.
“The furniture?”
“The Italian dining set.”
“Twelve years and that is what you ask me?”
His jaw tightened.
“The agreement says household contents need to be allocated.”
“Keep it.”
He smiled.
“Wine?”
“Keep it.”
“The cellar inventory is worth over thirty thousand.”
“Then enjoy it.”
His smile widened.
Jessica kicked me under the table.
Not hard.
A warning.
Do not antagonize him.
I went quiet.
Porsche.
His.
Lexus.
He wanted that too.
Jessica objected.
I did not.
“Give it to him.”
David laughed.
“You’re going to drive what?”
I looked at him.
“Something with no memory of you in it.”
That wiped away the laugh.
We moved on.
Accounts.
He wanted them.
We proposed transferring them subject to existing restrictions and claims.
His attorney asked several careful questions.
David became impatient.
“Richard, they’re giving us the accounts.”
Richard said, “I understand.”
“So take them.”
“We need to review restrictions.”
“They’re bank accounts.”
Martin, who attended part of the mediation, looked down at his notes.
I knew he was hiding a smile.
Richard did review.
That is important.
David’s attorney was not incompetent.
He received the disclosures.
He saw the debt schedules.
He explained them.
Later, he would insist on language acknowledging that each party had conducted independent due diligence and understood that asset values could rise or fall.
David signed.
Why?
Because he believed the development project would recover.
That was the part no one could have predicted perfectly.
David thought the risk was temporary.
He believed he could refinance.
He believed the Mesa center would stabilize.
He believed the pledged accounts would eventually be released.
He believed the Scottsdale house would continue appreciating.
And more than anything, he believed I was too emotional and financially ignorant to recognize future upside.
His confidence was not entirely irrational.
If everything broke his way, he might indeed do very well.
But that was never my game.
I was not betting against the assets.
I was refusing the bet entirely.
There was one more issue.
Business guarantees.
Some documents contained my signature.
That terrified me.
I did not remember signing them.
Not because David forged them.
At least we never proved that.
The reality was more humiliating.
Years earlier, David would put documents in front of me.
“Routine refinancing.”
“Spousal acknowledgment.”
“Community-property waiver.”
“Bank needs this.”
I signed some.
Not blindly, exactly.
I skimmed.
Asked questions.
Accepted his answers.
Martin found two guarantees where my exposure was disputed.
Jessica made release from those obligations a condition of the settlement.
David’s attorney resisted.
“Lenders control releases.”
“Then Mr. Vance will use commercially reasonable efforts and indemnify Claire until release.”
They argued over language for two weeks.
That language became the addendum.
The one David finally read in court.
It required him to assume responsibility for enumerated obligations tied to the house, pledged accounts, development companies, and vehicles.
It required him to indemnify me against specified business debts.
It required him to cooperate with refinancing, substitutions of collateral, or other steps needed to secure lender releases.
It stated explicitly that I made no representation about future value, collectability, liquidity, tax treatment, or business performance of the assets he received.
And most importantly:
If a listed creditor enforced a guarantee or collateral obligation against me because David failed to satisfy an allocated obligation, I retained a judgment right against him for reimbursement, fees, and enforcement costs.
David had wanted everything.
The addendum defined everything.
Assets.
Debt.
Risk.
Responsibility.
When he grinned in court, he was thinking about the first word.
His attorney whispered because the second half finally registered.
Outside the courtroom, David caught up with me before Jessica and I reached the elevator.
“What did you do?”
Jessica stepped between us.
“David, any questions should go through counsel.”
He ignored her.
“Claire.”
I looked at him.
His face was red.
Not the polished businessman from the hearing.
The real David.
Angry because something he controlled had moved without him.
“What did I do?”
“You buried all that debt language in an addendum.”
Richard appeared behind him.
“David.”
“No.”
He pointed toward me.
“She set me up.”
Jessica’s expression went cold.
“Your attorney received drafts twenty-three days ago.”
David spun toward Richard.
“You told me the debt allocation was standard.”
“I told you exactly what it did.”
“You said I was getting the accounts.”
“You are.”
“They’re pledged.”
Richard closed his eyes briefly.
“We discussed that.”
“No. You said there were restrictions.”
“That is what a pledge is.”
David looked at me again.
“You knew the Mesa loan was in trouble.”
“I knew what your documents said.”
“You knew.”
“Yes.”
His face changed.
Finally.
There it was.
Not the surprise over the addendum.
The realization that I had learned his secret.
“How long?”
“Before you asked for the divorce.”
That landed harder.
“You went through my business files.”
“I received a bank letter at our house listing our home as collateral.”
“That gave you no right—”
“To understand what my name and property were backing?”
His mouth closed.
Jessica stood beside me silently.
David lowered his voice.
“You think you’re clever.”
“No.”
“Then what is this?”
“You asked for everything.”
“That doesn’t mean—”
“You specifically wanted the house.”
“I built that house.”
“We both did.”
“I paid for most of it.”
“Then you should be thrilled.”
His jaw clenched.
“You wanted the accounts.”
He said nothing.
“The Porsche.”
Nothing.
“The savings.”
Nothing.
“You wanted everything except Sam.”
His face shifted.
That was the first time I used Sam’s name during the argument.
People passed us in the courthouse hallway.
Attorneys.
Families.
A deputy.
No one paid attention.
“You got exactly what you asked for,” I said.
David stared at me.
Then he said the sentence that proved he still did not understand.
“You kept your firm.”
“Yes.”
“That little design company.”
Jessica looked at me.
I could feel her trying not to react.
I smiled.
“Yes, David.”
He shook his head.
“So that’s it?”
“That’s it.”
“You’re going to walk away with a kid and some shares in a design shop while I carry millions in assets?”
I felt something release inside me.
He still saw wealth as the largest number on paper.
Maybe he always would.
“Yes.”
He gave a short, ugly laugh.
“Fine.”
Richard looked less confident.
He already knew Harlow’s valuation range from discovery.
David apparently had not paid attention to that either.
I almost told him.
Almost.
Then I decided it was not my job to educate him anymore.
The elevator arrived.
Jessica and I stepped inside.
David remained in the hallway.
Right before the doors closed, he said:
“You’ll regret this.”
I looked at him.
“No.”
The doors shut.
Jessica waited three seconds.
Then turned toward me.
“You are completely insane.”
I laughed.
“You’ve been saying that for months.”
“I still hate this settlement.”
“I know.”
“If his projects recover, he could have enormous upside.”
“I know.”
“You left real value.”
“I know.”
She looked at me.
“Then why are you smiling?”
Because for the first time in twelve years, David’s upside and downside were both David’s.
“I’m free.”
Jessica stopped talking….